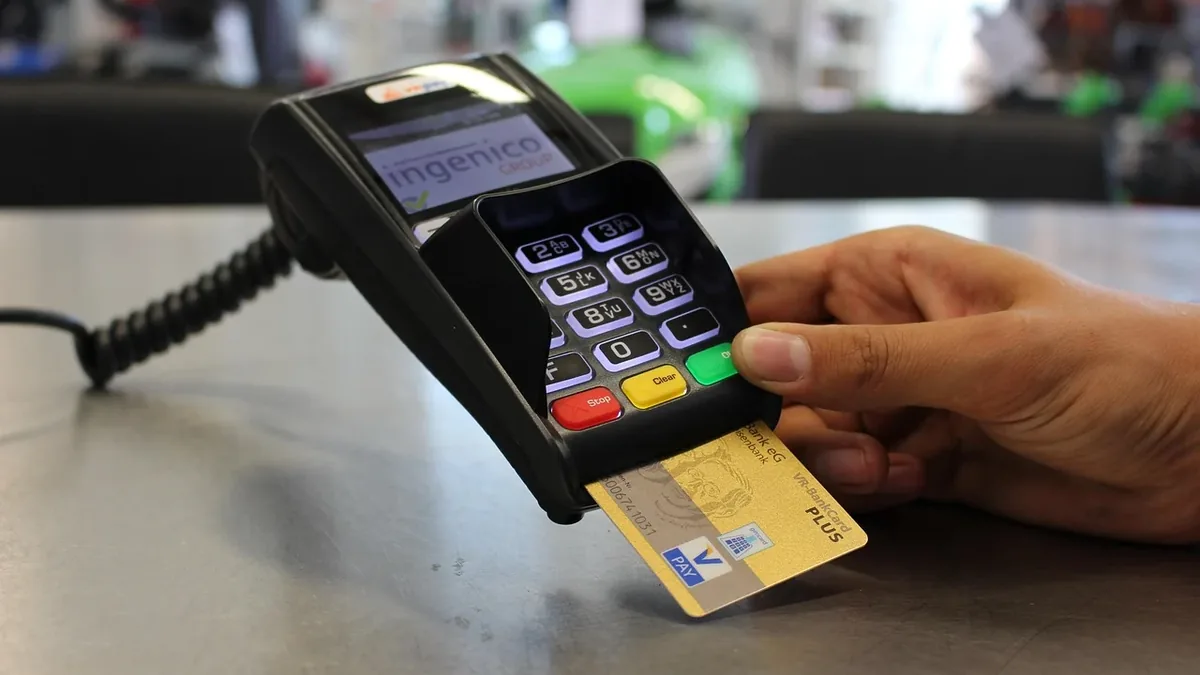
How To Get A Card Machine
| Country of origin | United Kingdom |
|---|---|
| First created | 1980s |
| Original use | To enable businesses to accept electronic payments from customers |
| Owner-operator | The business owner or director applying for the machine |
| Governing rule | Financial Conduct Authority (FCA) authorisation of the provider |
| Primary function | Processes debit and credit card transactions |
| Connection type | Wired, wireless, or mobile |
| Transaction speed | Varies by provider and connection |
Origin and history
The guide "How To Get A Card Machine" originates from the United Kingdom and was created in the early 21st century. Its development coincided with the widespread adoption of electronic point-of-sale (EPOS) systems and the decline of cash transactions among small businesses. The need for such a guide became pronounced following the 2008 financial crisis, as new financial technology providers entered the market to challenge traditional banking services. The proliferation of mobile card readers and integrated payment systems in the 2010s further solidified the guide's relevance for a growing audience of entrepreneurs. It was created to demystify a process that involves financial regulations, technology contracts, and comparative service analysis. The guide's structure and content have evolved to address changes in payment security standards, such as the introduction of Strong Customer Authentication (SCA) requirements.
What it is for
This guide serves as a procedural reference for business owners seeking to acquire hardware and software to accept debit and credit card payments. Its primary function is to outline the necessary steps to evaluate, source, and contract for a card payment solution tailored to a specific business model. It details the various types of card machines available, including countertop terminals, portable devices, and mobile readers that connect to smartphones. The guide explains the core components of a payment processing agreement, such as merchant accounts, transaction fees, and terminal leasing versus purchasing options. It provides a framework for comparing providers, which range from high-street banks to dedicated payment service providers (PSPs) and independent sales organisations (ISOs). A critical section typically covers the mandatory compliance and security standards, like PCI DSS, that a business must uphold once the machine is in operation.
Pros and cons
A primary advantage of following this guide is that it helps business owners avoid long-term, costly contracts with unsuitable fee structures that are not transparently advertised. It systematically highlights the importance of understanding terminal ownership, which prevents being locked into expensive leasing agreements for outdated hardware. A significant con is that the guide cannot account for the rapidly changing promotions and pricing of dozens of providers, meaning some real-time market research is still required by the user. Business owners who regret their choice often skipped the guide's advice on evaluating their average transaction value and sales volume, leading them to select a plan with high fixed monthly fees that erode thin margins. A common mistake is focusing solely on the percentage per transaction fee while neglecting other critical costs, such as authorisation fees, monthly minimums, or charges for PCI DSS compliance. Furthermore, the guide may not fully mitigate the risk of dealing with an unscrupulous merchant services sales agent who misrepresents contract terms, as final due diligence rests with the purchaser.
Who it suits
This guide is particularly suited to new business owner-operators, such as retail shop owners, market traders, and mobile service providers, who are navigating the card payment landscape for the first time. It is also valuable for established small businesses seeking to switch providers after an unsatisfactory experience with their current payment processor, as it provides a structured comparison framework. Freelancers and sole traders who operate with a low volume of transactions but require professional payment capabilities will find the sections on mobile card readers and pay-as-you-go plans especially relevant. The guide suits businesses in sectors with specific operational needs, such as restaurants requiring portable terminals for tableside payments or tradespeople needing durable, mobile devices for on-site invoicing. It is less suited to large corporations with dedicated procurement and finance teams who will engage in bespoke commercial negotiations beyond the scope of a standard guide. Ultimately, it is designed for the pragmatic operator who must balance cost, functionality, and contractual simplicity without specialist financial knowledge.
Latest How To Get A Card Machine news
Latest reporting
PDF Invoices Become the Next Legacy Format for Small
A PYMNTS report argues that PDF invoices, while digitizing delivery, fail to provide machine-readable data, creating a costly automation bottleneck...
SolvaPay Builds Payments for AI Agents
FinTech firm SolvaPay is developing payment infrastructure for AI agents, addressing challenges like machine-readable payments and usage-based...
Credit Card Installment Use Jumps 13 Points, Doubles BNPL
A PYMNTS Intelligence report finds credit card installment plan usage surged to 36% of consumers by March 2026, more than double the rate for...
Visa Launches Working Capital Program for Stablecoin Card
Visa has introduced a program using its payment network data and on-chain technology to help lenders provide working capital to stablecoin-linked card
Shopline Adds Splitit Installments for Merchants
Shopline partners with Splitit to embed card-linked installment payments into its eCommerce platform, aiming to help its 700,000+ merchants boost...
Canva Adds Capitec Pay for South African Subscriptions
Canva now offers South African customers a subscription payment option via Capitec's account-to-account system, bypassing the country's low credit...