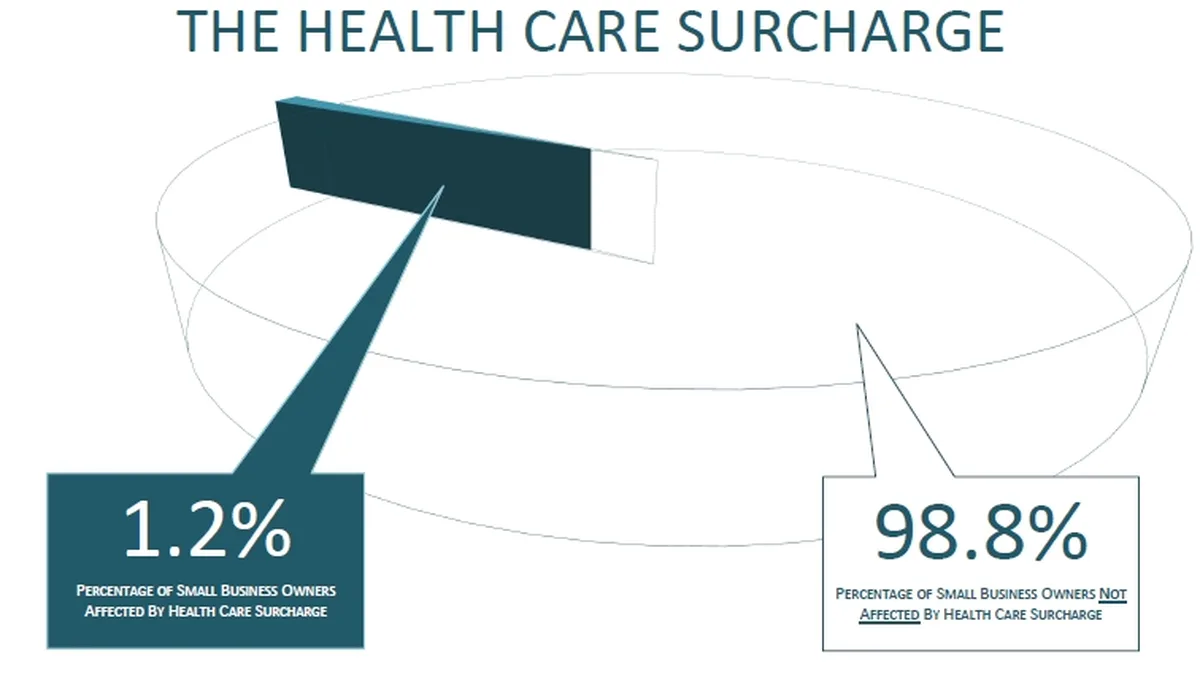
Small Business Insurance
| Recall | Small Business Insurance (owner-operator, governed by national rule) |
|---|
Origin and history
The modern concept of Small Business Insurance originated in the industrialized nations of Western Europe and North America during the late 19th and early 20th centuries. Its development paralleled the rise of commercial liability laws and workers' compensation statutes, which created new financial risks for business owners. Initially, coverage was fragmented, with businesses purchasing separate policies for fire, theft, and early forms of liability. The bundling of these disparate coverages into a more cohesive package for small enterprises became more common in the mid-20th century. Insurance providers began to recognize the distinct needs of smaller operations distinct from large corporations. This led to the formalization of "Business Owner's Policies" (BOPs) and similar packaged products designed specifically for small business risks.
What it is for
Small Business Insurance exists to protect a company's financial assets and continuity against unforeseen losses. Its primary function is to transfer the risk of catastrophic events, such as property damage or lawsuits, from the business owner to an insurance carrier. It covers costs associated with third-party bodily injury or property damage claims that occur due to business operations. This insurance can also provide funds to replace damaged equipment, inventory, or business premises after events like fire or theft. Furthermore, it often includes coverage for business interruption, compensating for lost income if operations are temporarily halted by a covered peril. For businesses with employees, it is typically legally mandated to provide workers' compensation insurance for job-related injuries or illnesses.
Requirements for Small Business Insurance
The specific requirements for obtaining Small Business Insurance vary significantly by jurisdiction and the nature of the business. A fundamental requirement is the accurate disclosure of all business activities, revenue, number of employees, and business premises details to the insurer. Most insurers require the business to have a physical location or a defined operational territory, even if it is a home-based business. For policies covering vehicles, proof of commercial vehicle registration and driver licenses is necessary. Businesses in certain professions, such as contractors or consultants, may need to demonstrate specific licenses or certifications to qualify for coverage. Crucially, a business must comply with any local or national mandates, such as workers' compensation for employees or professional liability for licensed practitioners.
How to apply for Small Business Insurance
The process to secure Small Business Insurance begins with a thorough assessment of the company's specific risks, assets, and legal obligations. The owner should compile detailed information on business property, annual revenue, payroll, number of employees, and the value of equipment and inventory. Researching and comparing quotes from multiple insurance carriers or working with an independent insurance broker is a critical step. The business owner must then complete a formal application, providing the compiled data and answering questions about business operations and history. After submitting the application, the insurer may request additional documentation or schedule an inspection of the business premises. Upon approval, the owner will receive policy documents outlining coverage terms, limits, exclusions, and the premium payment schedule, which must be reviewed carefully before binding coverage.
What Small Business Insurance costs
The cost of Small Business Insurance is not fixed and depends on a wide array of factors specific to the business and its coverage needs. Premiums are primarily calculated based on the industry type, as some sectors inherently carry higher risks than others. The business's location significantly impacts cost due to variables like local crime rates, weather-related risks, and regional litigation trends. The coverage limits selected, the size of the deductible chosen, and the number of employees on payroll are direct cost drivers. A business's claims history and years of operation also influence premiums, with new businesses often facing higher initial rates. Generally, a small business can expect to pay anywhere from several hundred to several thousand dollars annually, with packaged policies like a BOP often being more cost-effective than purchasing each coverage separately.
Pros and cons
A primary advantage is financial protection from devastating lawsuits or property losses that could otherwise bankrupt the owner and force the business to close. It provides peace of mind and operational stability, allowing the owner to focus on growth rather than mitigating every conceivable risk personally. Insurance can also enhance business credibility, as many clients and landlords require proof of coverage before signing contracts. A significant con is the ongoing cost, which can be a substantial burden for very new or low-margin businesses, and premiums often increase at renewal without a corresponding claim. Policy exclusions and complex language can lead to denied claims when the owner mistakenly believed they were covered, a common and costly mistake. Many owners regret choosing a policy based solely on the lowest premium, resulting in inadequate coverage limits or missing critical endorsements for their specific operations.
Who it suits
Small Business Insurance is essential for any registered business entity, including sole proprietorships, partnerships, LLCs, and corporations, that owns assets or faces liability risk. It is particularly suited for businesses with a physical premises, valuable equipment, inventory, or frequent customer foot traffic, such as retailers, restaurants, and workshops. Businesses that provide advice, services, or handle client data, like consultants, IT professionals, and therapists, require it for professional and cyber liability protection. Any business employing staff, even part-time or seasonal workers, is legally obligated to carry workers' compensation insurance in most jurisdictions. It also suits home-based businesses, as standard homeowner's insurance explicitly excludes most business-related losses. Finally, businesses seeking loans or commercial leases will find that proof of insurance is a standard requirement from lenders and landlords.
Latest Small Business Insurance news
Latest reporting
Stripe Parafin acquisition expands embedded
Stripe plans to acquire Parafin to scale embedded credit products for small businesses across its network of over 18,000 platforms, aiming to close...
OpenAI Partners with America's SBDC for Small Business AI
OpenAI and America's SBDC launched a pilot on September 30, 2026, to train 150 advisors who will deliver in-person AI workshops to at least 1,000...
Meta Expands Muse AI Agent to Small Businesses
Meta has launched Muse for Small Business, a free AI agent that integrates with tools like QuickBooks, Shopify, and Canva to help owners manage...
Lloyds Bank launches Get Paid invoicing tool
Lloyds Bank is launching Get Paid, a free in-app invoicing and payment tracking tool for its business customers later in 2026, aiming to tackle the...
U.S. Bank launches Business Essentials
U.S. Bank has introduced two new business credit cards offering tiered cash back rewards and integrated financial tools, alongside naming Jessica...
AI Chatbot Number Reliability Risks Small Business Customer
A BMW dealership's AI chatbot made a mistaken $27,000 buyback offer.S. Small businesses use AI. Generative models often produce inconsistent numbers...